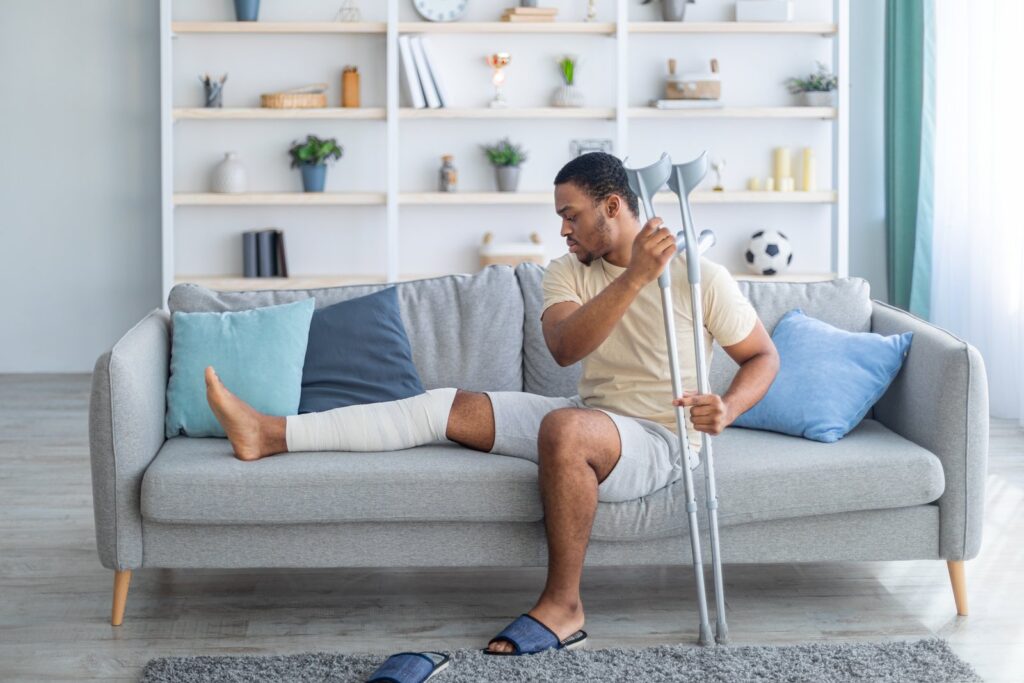
When a back injury keeps you from mowing the lawn or a shoulder tear makes it impossible to lift your toddler, the loss goes beyond a paycheck. That may leave you wondering what it costs to hire someone to do the laundry, cook dinner, or drive the kids to school when you can no longer manage those tasks yourself, and who should pay for it.
At Setareh Law, we know that personal injury claims involve more than medical bills and missed work. When an accident takes away your ability to perform everyday household tasks, that loss has a real dollar value, and we work to make sure it is accounted for in every settlement we pursue on your behalf.
What Counts as Household Services?
Household services cover the practical work that keeps a home running. This includes cooking, cleaning, laundry, yard maintenance, grocery shopping, home repairs, and childcare. Courts recognize these tasks as having a market value because a person could be paid to perform them, which sets household services apart from more personal, noneconomic losses like companionship.
Insurance adjusters often overlook this category or lump it into a vague pain and suffering figure. We separate it out and calculate it on its own so you are not shortchanged. Documentation matters here, which is why we ask our clients to keep track of what they used to do around the house, how often they did it, and what has changed since the injury.
How These Losses Are Calculated
The most common approach is the replacement cost method, which asks a simple question: what would it cost to hire someone to do what you can no longer do? If a housekeeper charges a certain hourly rate and you need 10 hours of help per week during your recovery, that rate multiplied by those hours becomes part of your claim.
A less common approach, the opportunity cost method, looks at the wages you gave up by spending time on household tasks instead of paid work, though this method is used less often because it can undervalue the labor involved. According to research from the Bureau of Labor Statistics time use data, the government tracks how Americans spend time on household activities and unpaid work, data that has been used to measure the broader economic value of tasks like these.
Short-Term vs. Long-Term Losses
For injuries with a clear recovery timeline, the calculation is fairly direct. We add up the weeks you needed help and multiply by a reasonable hourly rate.
Long-term or permanent injuries require a different method. If a spinal cord injury or traumatic brain injury means someone will need ongoing help around the house for years or for life, an economist may need to project those costs forward and adjust for inflation and life expectancy.
Building Evidence for Your Claim
Strong claims for household services rely on more than a general statement that you used to do more before the accident. We help clients gather:
- Witness statements: Family members or roommates can describe what you did before the injury and what has changed.
- Medical records: Documentation can link your physical limitations to specific tasks you can no longer safely perform.
- Receipts: Invoices from housekeepers, landscapers, or other hired help show the actual replacement cost.
- Time logs: A simple log of hours needed for outside help each week strengthens the calculation.
This evidence turns household services from an abstract idea into a concrete number the insurance company has a harder time dismissing. Without it, adjusters are more likely to minimize or ignore this part of your damages entirely.
Why This Damage Category Gets Overlooked
Household services losses are easy to underestimate because they do not come with a pay stub attached. Someone who could not perform their job might have a clear lost wages figure, but someone who can no longer garden or handle home repairs on weekends often assumes there is nothing to claim.
This is especially true for stay-at-home parents and retirees, whose contributions to a household seldom show up on tax forms but still carry real economic value. We have seen cases where a spouse’s unpaid labor at home represented a substantial part of the family’s actual financial picture, even though no income was ever reported for that work.
How Setareh Law Fights for Full Compensation
Setareh Law has recovered over $400 million for injured Californians, and we know how to identify every category of loss in a case, including the ones insurance companies are hoping you will overlook. Our team draws on 60 years of combined experience to build claims that reflect the full impact an injury has on your daily life, not just your medical bills.
We handle every case on a contingency fee basis, so you only pay a fee if we get you results. If your injury has changed how you manage your home, reach out through our contact form to talk with our team about what your claim may be worth.